What Lawn Care Business Owners Need to Know About Quarterly Estimated Taxes
July 27, 2026 | By: Dan Ralphs
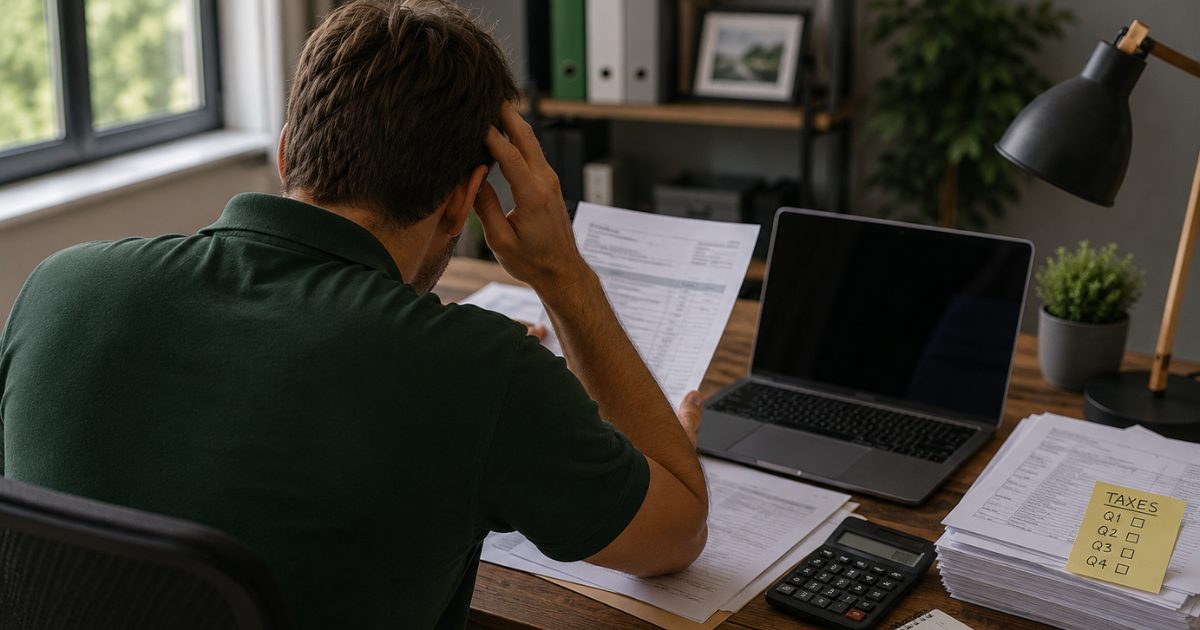
If you operate as an LLC, S-corp, or sole proprietor and pay yourself with anything other than a straightforward W-2 paycheck, the federal government expects you to pay estimated taxes four times a year — not one big bill every April.
Who Actually Has to Pay
If you expect to owe $1,000 or more in tax for the year after withholding, you’re generally required to make quarterly payments. For most lawn care business owners taking an owner’s draw or distribution, that’s you.
The Due Dates That Catch People Off Guard
Estimated payments are due roughly in mid-April, mid-June, mid-September, and mid-January — not evenly spaced by calendar quarter, which is exactly why so many owners miss the June and September dates.
How to Land on the Right Number
There are two common approaches:
Safe harbor: pay based on last year’s total tax liability (adjusted for growth), which protects you from penalties even if this year is different
Actual estimate: set aside a percentage of net profit each quarter based on your current year’s numbers
Either way, this only works if your books are current. You can’t estimate a tax payment off numbers that are three months stale.
Building the Habit
The simplest system: every time you take a distribution, move a set percentage of profit into a separate tax savings account. When the quarterly due date hits, the money’s already there — no scrambling, no dipping into payroll or materials budget to cover it.
Quick Answers
What percentage of profit should I set aside for taxes? It varies by entity structure, state, and personal tax situation — this is a conversation for your CPA, not a flat industry rule. Many owners land somewhere in the 25–30% range, but yours could be different.
What if my income is seasonal — do I still pay evenly across four quarters? You can use the annualized income method if your profit is heavily front- or back-loaded, which lets you match payments closer to when you actually earn the income. Talk to your CPA about whether this applies to you.
What happens if I underpay? You can be charged an underpayment penalty, calculated on the shortfall for each period. Safe harbor payments are the easiest way to avoid it entirely.
Want your books clean enough that your CPA can nail your estimated payments every quarter?
SHARE THIS
Have questions about our bookkeeping services
or fit for your business?
Grow Smarter with Expert Help
© Copyrights by The Lawn Care Books.
All Rights Reserved.
© Copyrights by The Lawn Care Books. All Rights Reserved.
Grow Smarter with Expert Help