Cash Flow vs. Profit:
Why Your Lawn Care Business Can Be Profitable and Still Broke
June 02, 2026 | By: Dan Ralphs
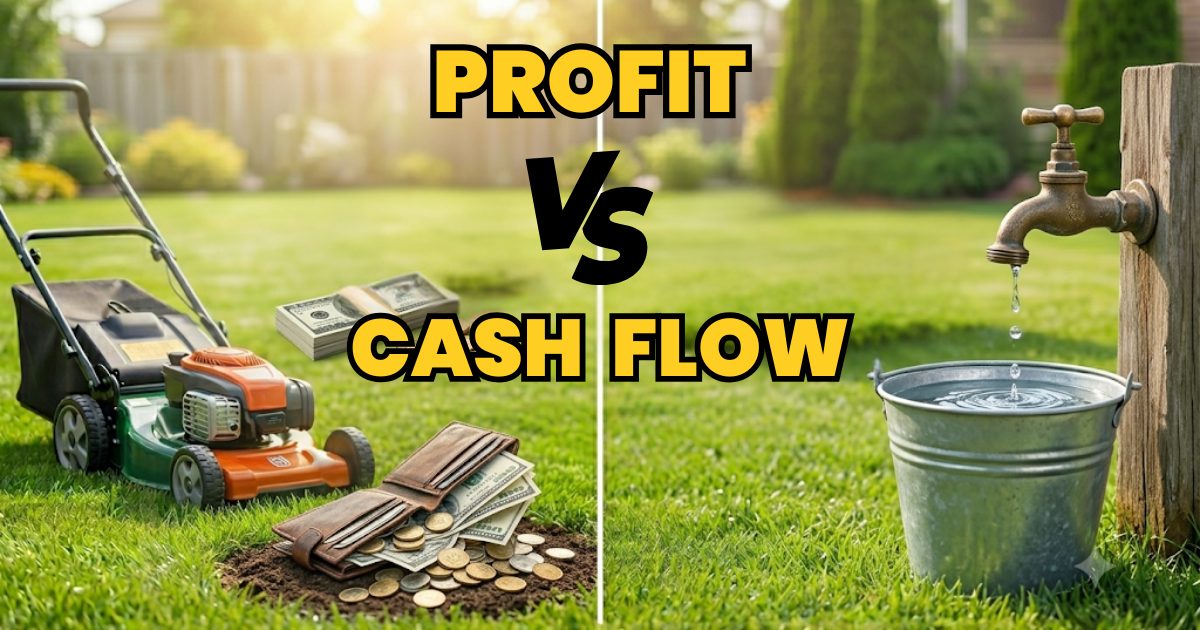
The Confusing Truth About Profitable Businesses That Run Out of Cash
Here's a scenario that trips up lawn care business owners every single spring.
The business did well last year. The P&L shows a net profit. And yet, in March and April — right when the season is ramping up and they need cash most — the bank account is thin.
They're not doing anything wrong. Their business isn't failing. But they're about to have a very stressful few months because they don't understand the difference between profit and cash flow.
What Profit Means — and What It Doesn't
Profit is an accounting concept. It measures the difference between revenue and expenses over a period of time. If your revenue is $500,000 and your total expenses are $400,000, your profit is $100,000.
But profit doesn't tell you when the cash actually arrived — or when it actually left. A customer who owes you $10,000 and hasn't paid yet still shows up as revenue on your P&L. A truck payment you made in January is a cash outflow that doesn't hit your P&L the same way.
Cash flow is about timing. And in a seasonal business like lawn care, timing is everything.
The Three Seasons of Lawn Care Cash Flow
Most lawn care businesses follow a predictable cash flow pattern:
Winter is a cash draw-down period. Revenue is low or zero. Expenses — insurance, equipment loans, salaried staff — keep running. Cash reserves shrink.
Spring is a cash crunch period. Revenue starts picking up, but it takes time to collect. Meanwhile, you're buying materials, paying new hires, fueling trucks — all before the checks come in.
Summer and fall are cash accumulation periods. Revenue is strong and collections are current. This is when you rebuild the reserves you drew down in winter and spring.
If you know this pattern is coming every year, you can plan for it. If you don't, it will surprise you every time.
What the Cash Flow Statement Actually Shows You
The cash flow statement is the third of the three financial reports every lawn care business owner should read — and the one most often ignored.
It breaks down cash movement into three categories: operating activities (day-to-day business), investing activities (equipment purchases, major assets), and financing activities (loans, owner draws).
The number to watch is net cash from operations. If that number is consistently negative even during your peak season, something is structurally wrong — either your pricing, your collections, or your cost structure.
How to Protect Yourself From the Spring Cash Crunch
The answer is reserves. Build cash during your high-revenue months specifically to cover the winter and early spring gap.
A rough rule: know what your monthly fixed costs are in your slowest months, and keep at least two to three months of those costs in a separate reserve account by the time October arrives.
That number looks different for every business. The only way to calculate it accurately is with clean books and a cash flow statement that actually reflects your business.
Worried about cash flow this season? Let's look at the full picture together.
SHARE THIS
Have questions about our bookkeeping services
or fit for your business?
Grow Smarter with Expert Help
© Copyrights by The Lawn Care Books.
All Rights Reserved.
© Copyrights by The Lawn Care Books. All Rights Reserved.
Grow Smarter with Expert Help